Navigating the financial side of renewable energy can be intimidating, but securing the right solar installation incentives is the single most effective way to shorten your system’s payback period. Whether you are a homeowner seeking to lower your utility bills or a small business owner looking for agricultural grants and tax write-offs, failing to optimize your incentive strategy can leave thousands of dollars on the table. This guide provides a comprehensive, step-by-step roadmap to understanding, stacking, and claiming federal, state, and local solar incentives under current 2026 regulations.
How do I maximize solar installation incentives?
- Research localized programs using the Database of State Incentives for Renewables & Efficiency (DSIRE) before requesting quotes.
- Purchase the system with cash or a loan. Leases and Power Purchase Agreements (PPAs) generally assign tax credits to the developer, not you.
- Verify installer credentials, as many utility rebates require the use of a NABCEP-certified professional.
- Sign an interconnection agreement with your utility early to lock in favorable net metering or net billing rates.
- Keep itemized records of all equipment and labor costs, and file IRS Form 5695 (residential) or the appropriate business tax forms to claim federal credits.
Key Takeaways
- Federal Credits are Active: The federal Residential Clean Energy Credit (Section 25D) remains at 30% through 2032. For businesses, the Section 48E Clean Electricity Investment Credit offers a base rate with potential bonus adders for domestic content or energy communities.
- Ownership Matters: You must own the solar array to claim federal tax credits and most state rebates.
- Incentives are Localized: State tax credits, property tax exemptions, and utility cash rebates vary drastically by zip code and utility provider.
- Timing is Crucial: Federal credits are claimed for the tax year the system is “placed in service” (turned on and approved), not the year you sign the contract or buy the panels.
- Seek Professional Advice: Tax rules change, and strict phase-outs or income limitations may apply. Always consult a qualified tax professional before making financial commitments based on tax credits.
Understanding the 2026 Solar Incentive Landscape
The financial viability of a solar power installation depends on a combination of federal tax policy, state legislation, and utility-level grid management. Understanding the framework of these programs is the first step toward maximizing your return on investment.
The Federal Residential Clean Energy Credit (Section 25D)
For homeowners, the most significant incentive is the Residential Clean Energy Credit under Section 25D of the Internal Revenue Code. As of 2026, this credit allows you to deduct 30% of your total solar installation costs from your federal tax liability.
- Eligible costs: Solar panels, inverters, racking, battery storage (with a capacity of at least 3 kilowatt-hours), sales tax, and labor costs for site preparation and installation. Roof replacements are generally not eligible unless the roofing material itself acts as the solar collector (like solar shingles).
- Non-refundable nature: This is a non-refundable tax credit. It reduces your tax bill dollar-for-dollar, but if the credit exceeds what you owe in federal taxes for the year, the IRS will not write you a check for the difference. However, you can roll the unused portion forward to subsequent tax years.
The Clean Electricity Investment Credit for Businesses (Section 48E)
For commercial installations, the tax landscape shifted for projects placed in service after December 31, 2024, transitioning to the Section 48E framework.
- Structure: This credit relies on a base rate, but businesses that meet prevailing wage and apprenticeship requirements can unlock a credit of up to 30%.
- Bonus Adders: Small businesses and agricultural producers can stack additional “bonus” percentages by utilizing domestic content (U.S.-made steel/iron and manufactured products) or by placing the project in a designated “energy community” (areas with historical reliance on fossil fuel industries).
Why Timing and Tax Years Matter
A common pitfall is misunderstanding the timeline. To claim a tax credit for the 2026 tax year, your system must receive permission to operate (PTO) from your utility by December 31, 2026. If you buy panels in November 2026, but the utility doesn’t approve interconnection until January 2027, you must claim the credit on your 2027 tax return.
Step-by-Step Guide to Maximizing Solar Installation Incentives
Securing every dollar requires strategic planning long before panels are attached to your roof. Follow these steps sequentially to ensure you do not inadvertently disqualify yourself from valuable programs.
Step 1: Assess Eligibility and Energy Goals
Before exploring incentives, determine your baseline eligibility.
- Tax Liability: Review your previous tax returns. Do you have enough federal tax liability to absorb a 30% credit? If you are retired and pay no federal income tax, the 25D credit holds no direct value for you, though you may still benefit from state or utility rebates.
- Property Type: Are you installing on a primary residence, a secondary home, or an investment property? Section 25D applies to primary and secondary homes, but rental properties typically fall under commercial depreciation (MACRS) and Section 48E rules.
Step 2: Research State, Local, and Utility Incentives
Federal credits apply nationwide, but the most lucrative combinations involve stacking federal credits with localized programs.
- State Tax Credits: States like New York, Massachusetts, and South Carolina offer their own solar tax credits, which can be claimed alongside the federal credit.
- Utility Rebates: Many local utilities offer upfront cash rebates based on the size of the system (measured in dollars per watt).
- Property and Sales Tax Exemptions: Solar installations add value to your home. Many states offer property tax exemptions so that this added value does not increase your annual property tax bill. Furthermore, numerous states waive state sales tax on solar equipment purchases.
- Actionable Advice: Use the Database of State Incentives for Renewables & Efficiency (DSIRE) at dsireusa.org. Enter your zip code to generate a comprehensive list of active programs in your jurisdiction.
Step 3: Choose the Right Ownership and Financing Model
Your financing method dictates who gets the incentives.
- Cash Purchase or Solar Loan: You own the system. You are eligible for the federal tax credit, state credits, and you retain the rights to the system’s power and any Solar Renewable Energy Certificates (SRECs).
- Solar Lease or Power Purchase Agreement (PPA): The solar developer owns the system and sells you the power (or leases you the equipment). The developer claims the tax credits and depreciation. While a PPA might offer zero down and immediate bill reductions, you forfeit the primary financial incentives.
Step 4: Select and Vet Qualified Solar Installers
Rebate programs have strict quality control standards. If your installer lacks the proper credentials, your rebate applications will be denied.
- Certifications: Many state and utility incentives require the lead installer to hold certification from the North American Board of Certified Energy Practitioners (NABCEP).
- Itemized Quotes: Require your installer to break down equipment, labor, and battery storage costs. If you install an electrical panel upgrade alongside solar, only the portion of the upgrade necessary for solar is tax-deductible. Itemized invoices are critical for IRS compliance.
Step 5: Confirm Incentive Requirements Before Signing
Never sign a solar contract under high-pressure sales tactics, and do not assume your installer will handle all rebate paperwork automatically.
- Read the Fine Print: Establish in writing who is responsible for filing the utility rebate and interconnection applications.
- Pre-Approval: Some utility rebate programs require pre-approval before any installation work begins. Installing first and asking for a rebate later will result in a rejection.
Step 6: Navigate Installation, Inspection, and Interconnection
Once installed, your system must pass a municipal building inspection and a utility inspection.
- Permission to Operate (PTO): You cannot legally turn on your system until the utility issues PTO. The date of your PTO is the official “placed in service” date for tax purposes.
- Documentation: Keep copies of the building permit, the signed interconnection agreement, the final invoice marked “Paid in Full,” and the manufacturer’s specification sheets for your panels and inverters.
Step 7: Claim and Document Your Incentives
When tax season arrives, it is time to monetize your research.
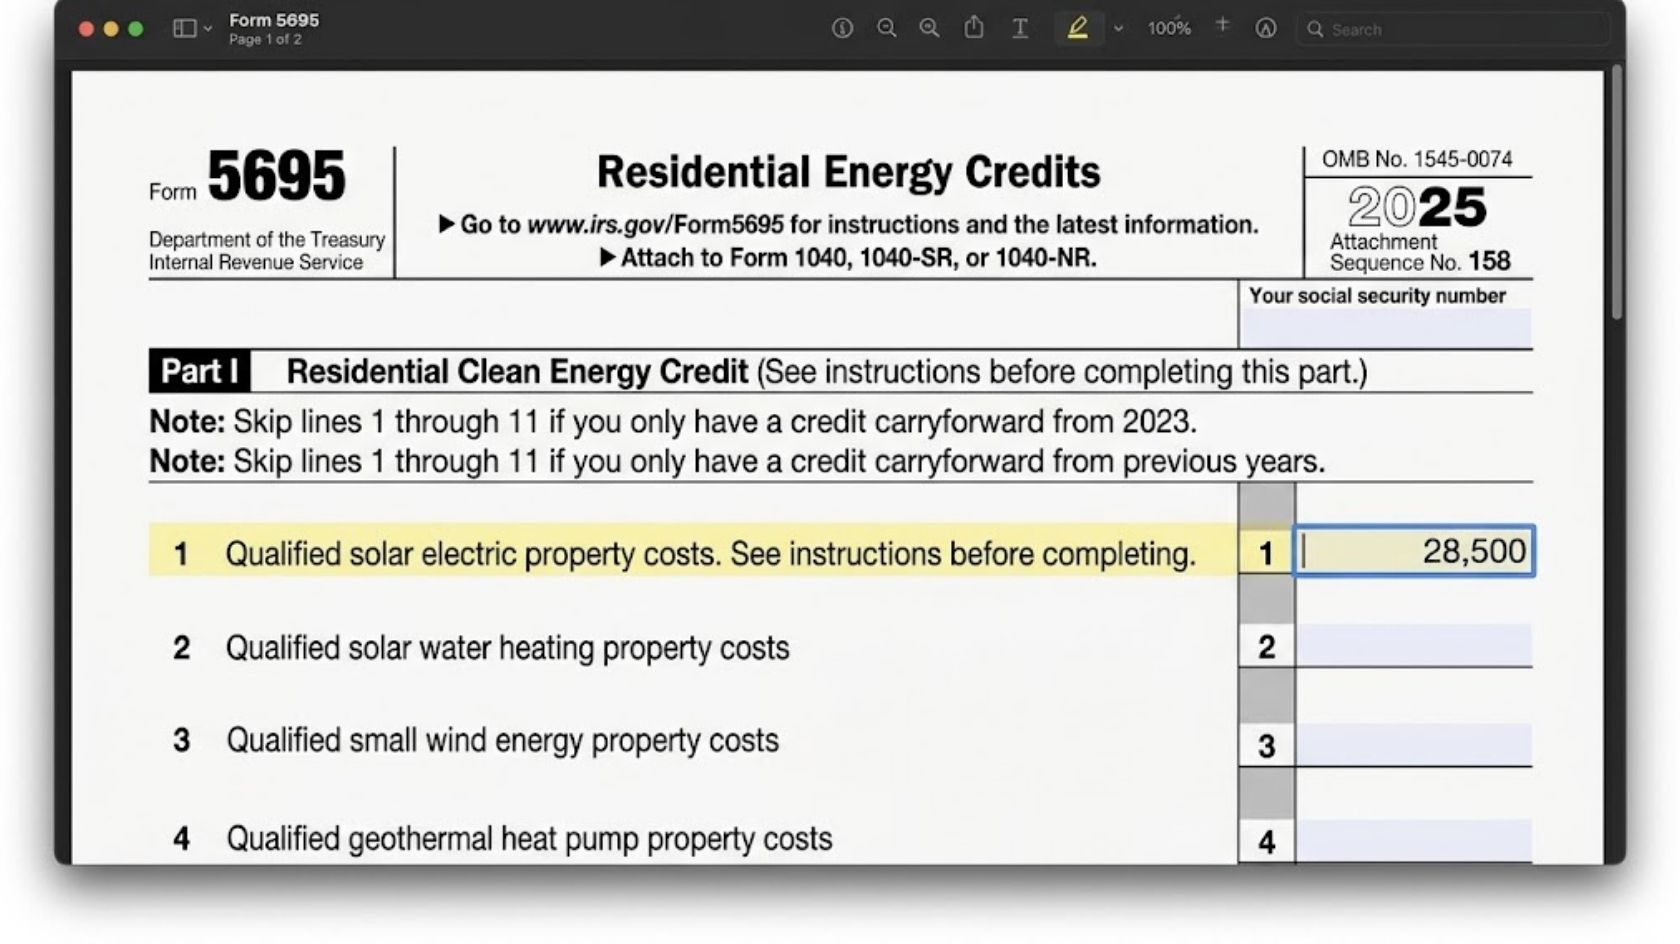
- Residential Claims (IRS Form 5695): Homeowners use Form 5695, “Residential Energy Credits,” to calculate their 25D credit. The final credit amount is then carried over to Schedule 3 (Form 1040).
- Commercial Claims: Businesses must navigate Form 3468 to claim the Section 48E credit, properly documenting prevailing wage compliance and any bonus adders. Businesses can also leverage the Modified Accelerated Cost-Recovery System (MACRS) to deduct the depreciating value of the solar asset over five years.
- USDA REAP Grants: Rural small businesses and agricultural producers can apply for the Rural Energy for America Program (REAP), which provides guaranteed loan financing and grant funding for renewable energy systems.
Step 8: Maximize Long-Term Value (Net Metering & SRECs)
Incentives do not stop once the system is installed.
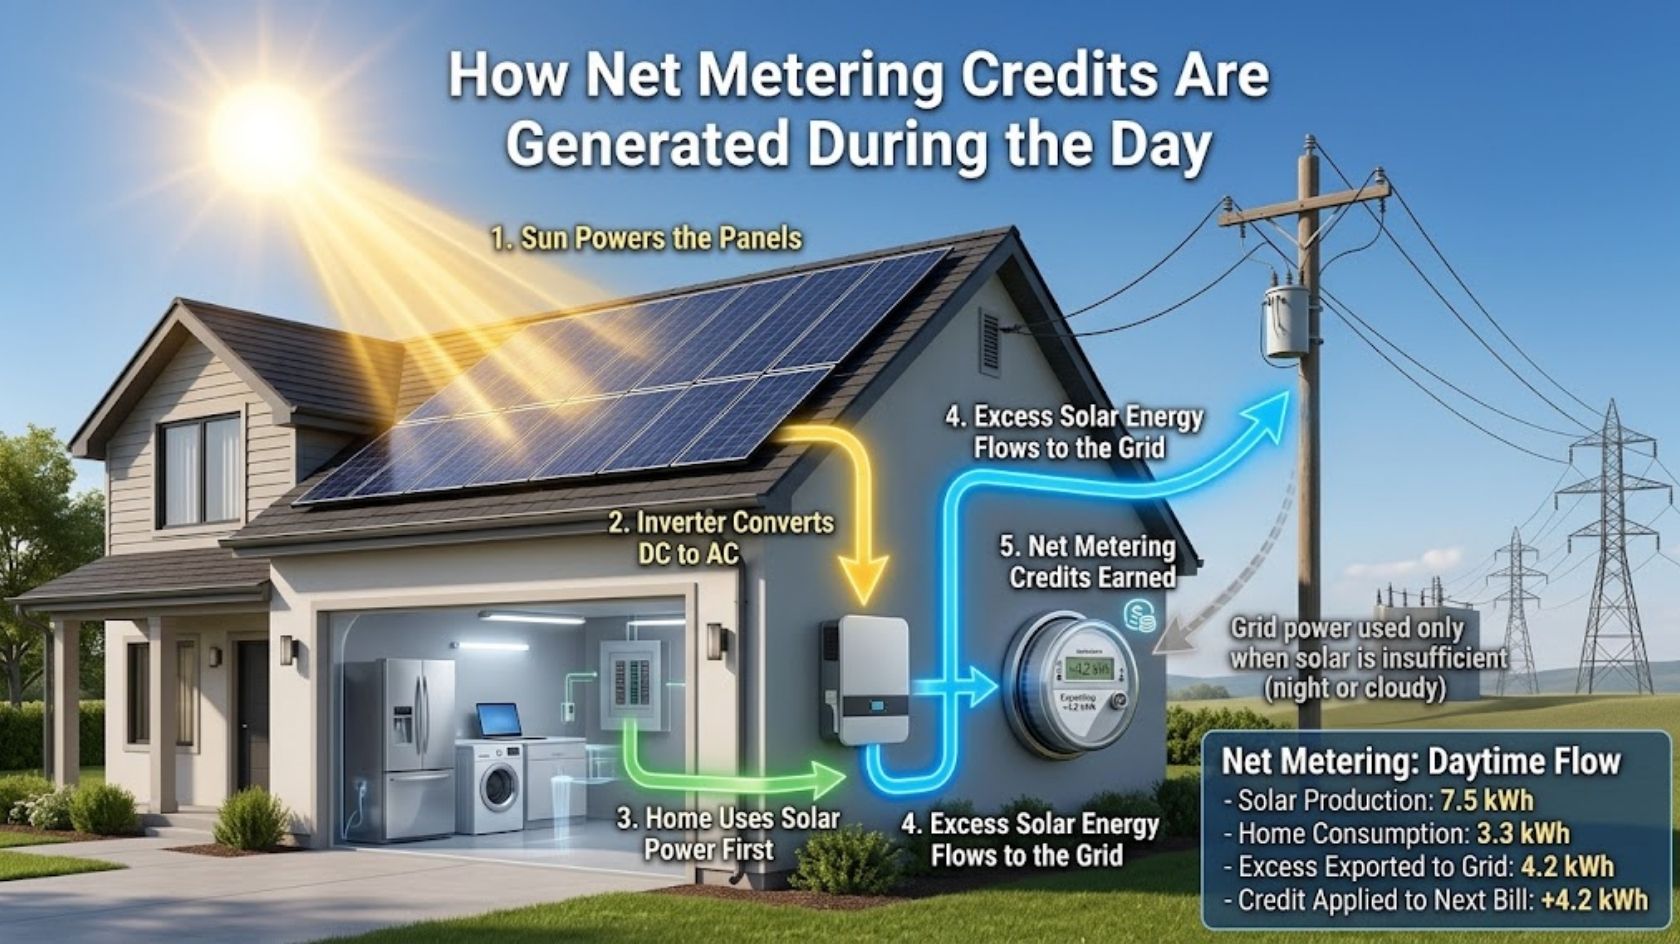
- Net Metering / Net Billing: This utility policy governs how you are compensated for excess electricity sent back to the grid. Under traditional net metering, you receive a 1-to-1 kilowatt-hour credit. Under newer net billing frameworks (like California’s NBT/NEM 3.0), export rates are tied to wholesale market prices, making solar battery storage essential for maximizing ROI.
- SRECs: In states with Renewable Portfolio Standards (RPS) markets (such as New Jersey, Pennsylvania, and Maryland), your system generates one Solar Renewable Energy Certificate (SREC) for every megawatt-hour of electricity produced. You can sell these certificates on the open market, generating passive income for years.
Comparison Table: Types of Solar Incentives
| Incentive Type | Who Qualifies? | Typical Value | How to Claim |
|---|---|---|---|
| Federal Clean Energy Credit (25D) | Homeowners who purchase their system | 30% of system cost | File IRS Form 5695 with federal taxes |
| Federal Investment Credit (48E) | Commercial, agricultural, non-profits | Base rate + potential bonus adders up to 30%+ | File IRS Form 3468 with business taxes |
| State Tax Credits | Residents of participating states | Varies (e.g., $1,000 – $5,000 cap) | File appropriate state tax forms |
| Utility Rebates | Customers of participating utilities | Typically $0.20 – $1.00 per watt upfront | Application submitted by installer to utility |
| SRECs | Owners in RPS market states | Variable market rate per MWh produced | Register with state tracking system/broker |
| MACRS Depreciation | Commercial system owners | Accelerated tax deduction over 5 years | Claimed on business tax returns |
Common Mistakes That Reduce Incentive Value
Even diligent property owners make structural errors that leave money on the table. Be wary of these widely observed industry pitfalls:
- Leasing when you have tax liability: Signing a lease simply because it requires no money down, inadvertently giving a 30% tax windfall to a third-party developer.
- Misunderstanding non-refundable credits: Assuming the IRS will send a $10,000 check if you only owe $4,000 in federal income taxes. (The remaining $6,000 rolls over to the next year, but you don’t get it as cash).
- Applying credits to the gross cost incorrectly: If you receive a $2,000 state rebate before calculating your federal tax credit, you must deduct the rebate from the total system cost first. (e.g., $30,000 system – $2,000 rebate = $28,000 eligible for the 30% federal credit).
- Failing to register for SRECs: Assuming SRECs are credited to your utility bill automatically. SRECs are a separate commodity market and require registration through a broker or state aggregator.
Illustrative Example: Stacking Solar Incentives
To understand how these programs interact, consider this illustrative residential example. (Note: This is a hypothetical scenario; actual tax implications depend on individual financial circumstances).
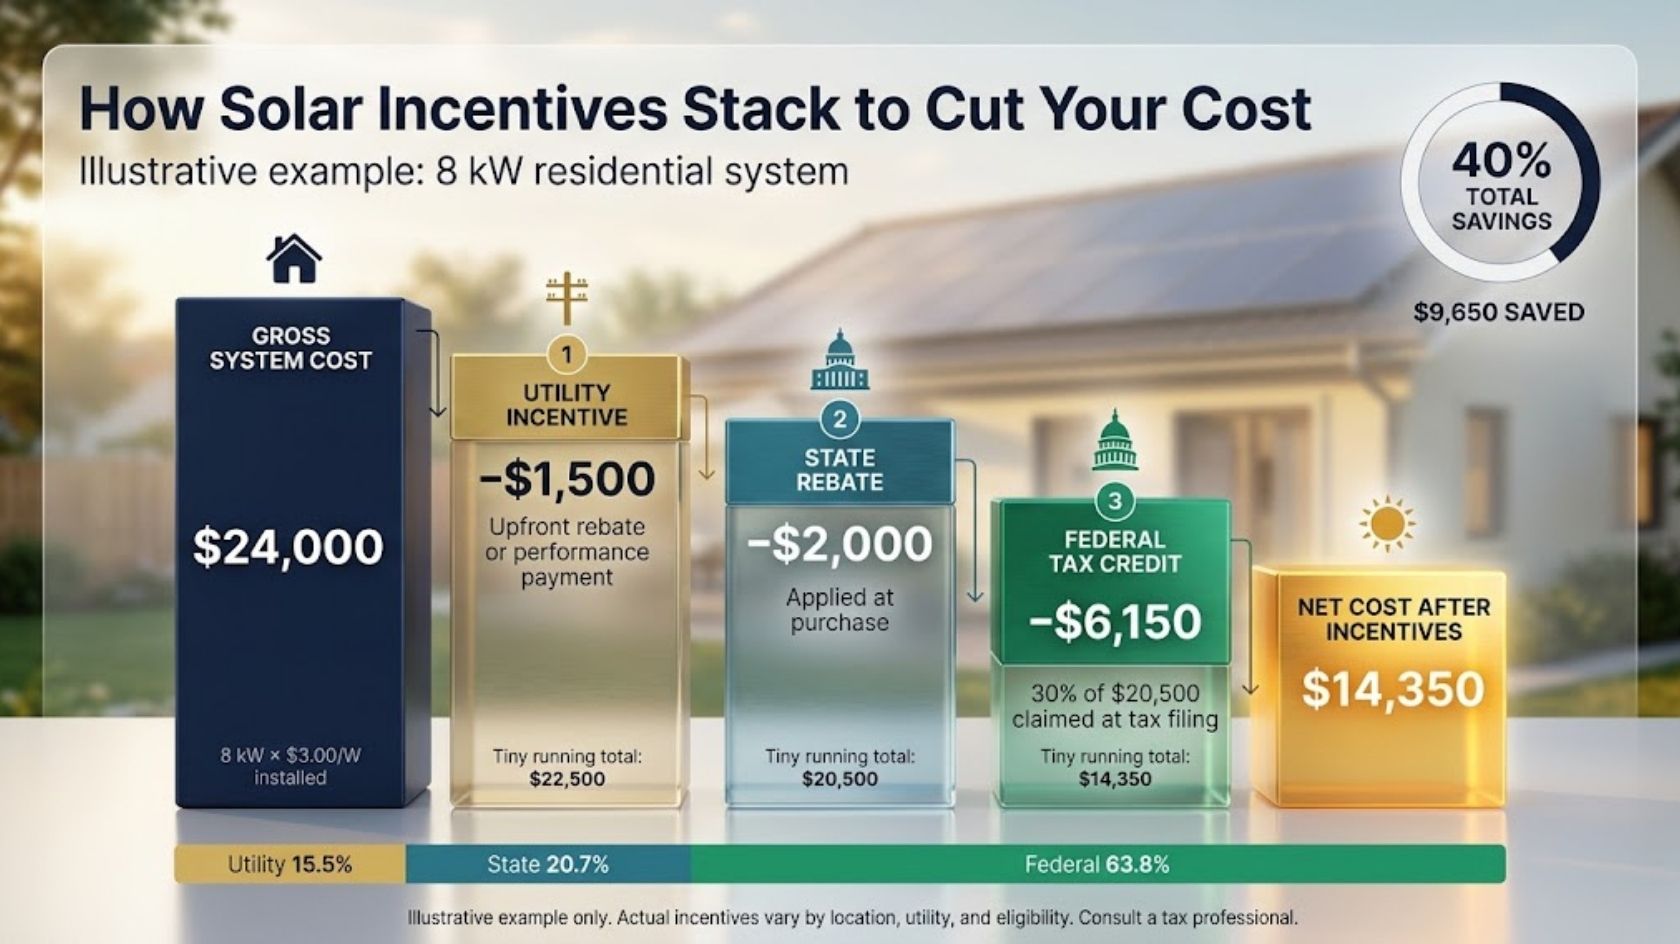
- Gross System Cost: $30,000 (Equipment and labor)
- Utility Cash Rebate: $1,500 (Paid shortly after installation)
- Net Cost for Tax Purposes: $28,500
- State Tax Credit (Example State: 10% capped at $1,000): $1,000 deduction on state returns
- Federal Tax Credit (30% of $28,500): $8,550 deduction on federal returns
Total Out-of-Pocket Cost After Incentives:
$30,000 – $1,500 – $1,000 – $8,550 = $18,950
In this example, stacked incentives reduced the upfront cost of the system by more than a third. Furthermore, if the system offsets $2,000 worth of utility electricity per year through net metering, the payback period drops to roughly 9.5 years.
Frequently Asked Questions (FAQ)
Yes. As long as you purchase the system using a solar loan, home equity loan, or personal loan, you are considered the owner and are eligible to claim the tax credit. You cannot claim the credit if you sign a solar lease or Power Purchase Agreement (PPA).
The Residential Clean Energy Credit is non-refundable. If your credit is $9,000 but your federal tax liability for the year is only $5,000, your tax bill drops to zero. The remaining $4,000 credit rolls forward to the next tax year.
No. The federal solar tax credit is applied against the taxes you owe. It may result in a refund when you file your taxes if you had standard paycheck withholdings throughout the year, but the government does not send a direct stimulus-style check for the solar credit itself.
Yes. Under current law, standalone battery storage systems with a capacity of 3 kilowatt-hours or more qualify for the 30% federal tax credit, even if they are not installed at the same time as the solar panels.
In many jurisdictions, no. Most states have enacted property tax exemptions for renewable energy systems. This means that while the solar panels increase the resale value of your home, your local tax assessor will not include that added value when calculating your annual property tax bill.
Ask the installer for their NABCEP (North American Board of Certified Energy Practitioners) certification number, their state contractor license, and proof of insurance. Verify these credentials with your state energy office or utility provider’s list of approved vendors.
Conclusion and Next Steps
Maximizing your solar installation incentives requires proactive research, precise timing, and a clear understanding of your personal tax liability. By taking the time to map out federal credits, state exemptions, and local rebates before signing a contract, you can drastically reduce the cost of your transition to renewable energy.
Your immediate next step: Look up your zip code in the DSIRE database and consult with a certified tax professional to verify how current tax policies apply to your specific financial situation. Armed with this knowledge, you can confidently request itemized quotes from highly rated, NABCEP-certified solar installers in your area.
Sources and Further Reading
- U.S. Department of Energy (DOE): Homeowner’s Guide to the Federal Tax Credit for Solar Photovoltaics (Energy.gov)
- Internal Revenue Service (IRS): Form 5695 (Residential Energy Credits) and Instructions (IRS.gov)
- DSIRE: Database of State Incentives for Renewables & Efficiency (DSIREUSA.org)
- U.S. Department of Agriculture (USDA): Rural Energy for America Program (REAP) (USDA.gov)
- National Renewable Energy Laboratory (NREL): State and Local Planning for Energy (NREL.gov)